Start with the same questions for every asset
The quickest way to lose objectivity is to let each file tell its own story. A clean portfolio review starts with the same checklist for every company, property, or mixed-use asset: who owns it, who controls it, what income supports it, and what could interrupt that income. If one deal is in Johannesburg and another in Durban, the location changes, but the core questions should stay fixed.
Ask whether the asset has a clear legal identity, whether the title or company records match the seller’s story, and whether the income shown is backed by current documents. For lenders, the question is not only “Can this asset service debt?” It is also “What would happen if the tenant leaves, the accounts are late, or a director dispute appears?”
- Use the same review template for every asset in the batch.
- Compare like with like: vacant occupation, leased occupation, or owner-occupied.
- Record every gap, even if it looks minor at first.
Weight risk instead of counting issues
Not every problem matters equally. A missing municipal account is irritating, but a disputed ownership trail or unexplained director change can be far more serious. In a portfolio setting, the better approach is to weight each issue by its likely effect on value, enforceability, and recoverability.
A practical method is to group findings into three bands. Low-risk items are admin matters that can be corrected quickly. Medium-risk items affect timing or pricing. High-risk items can stop a transaction, delay registration, or weaken security for a lender. This keeps you from overreacting to small gaps and underestimating the bigger ones.
- High risk: ownership mismatch, pending litigation, false occupancy claims, major financial distress.
- Medium risk: outdated compliance documents, unverified turnover, weak tenant concentration.
- Low risk: missing copies, small filing gaps, minor address differences.
Look for concentration across the full book
A portfolio can look healthy on paper and still carry too much exposure to one suburb, one tenant type, or one business sector. That is a common issue in Gauteng where several assets may sit in similar nodes such as Centurion, Midrand and Sandton, but still be tied to the same economic drivers. If office demand softens or one industry slows, the whole book can feel the pressure.
Property and company reviews should therefore check concentration in several ways. Are three of the five assets dependent on one tenant group? Are multiple borrowers reliant on the same cash-flow source? Is the portfolio too exposed to one municipal area with service delivery problems or changing rates bills? These are not abstract questions, they affect income stability and exit timing.
- Tenant concentration by person, group, or sector.
- Geographic concentration by town, node, or province.
- Funding concentration by lender, guarantor, or related party.
Use local evidence, not just documents
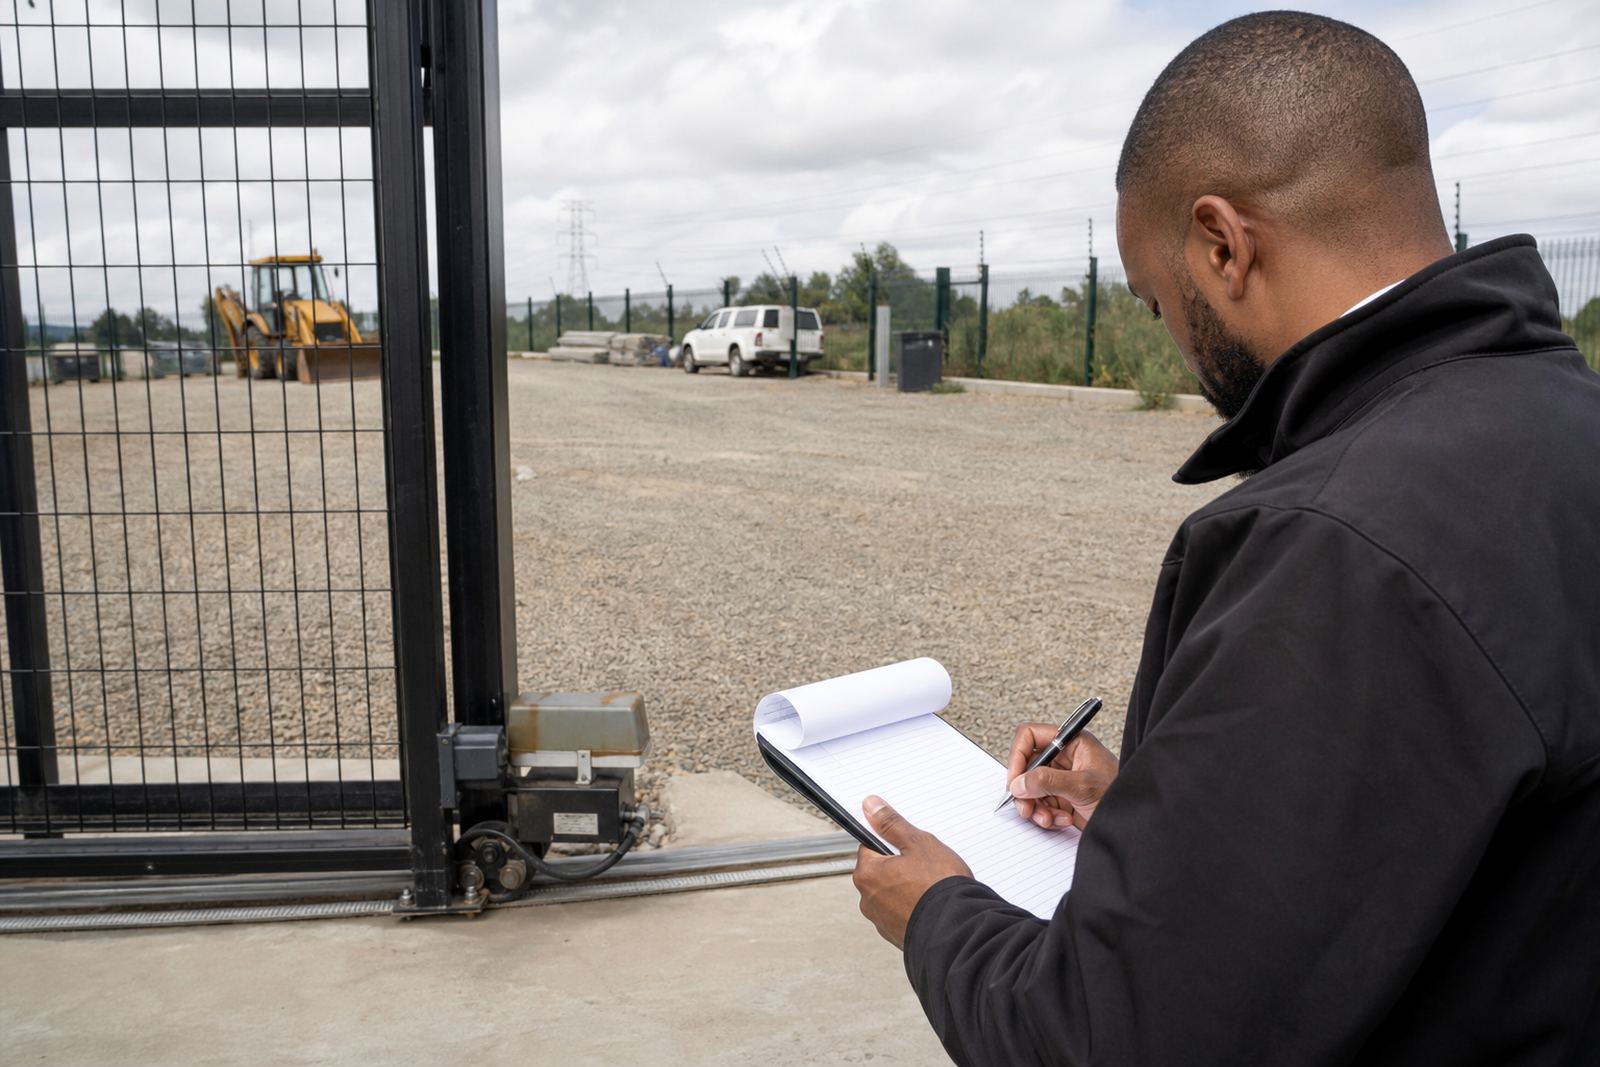
Paperwork gives one part of the picture. Site verification and local checks give the rest. A property may show full occupancy in a file, yet a physical visit can reveal empty bays, informal use, or a tenant who is still there but not paying. In some parts of South Africa, especially where load-shedding affects trading hours or coastal humidity affects maintenance, those practical conditions matter as much as the lease summary.
For company assets, field confirmation helps confirm that the business is active at the stated address and that operations match the reported scale. A lender reviewing multiple files will often spot the same weakness again and again: the file says one thing, the site tells another. That is where verification work saves time and money.
- Match the occupation status to what is observed on site.
- Check signage, access, security, and obvious trading activity.
- Note whether the premises appear maintained, closed, or partially used.
Compare cash flow quality, not only cash flow size
Two assets can produce the same income, but not the same quality of income. One may rely on a single tenant with a long, clean payment record. Another may depend on short leases, irregular renewals, or income that jumps around from month to month. For buyers and lenders, cash flow quality often matters more than gross yield.
When reviewing a portfolio, ask how predictable the income is, how much of it is documented, and how easy it would be to replace if it disappeared. A rent roll with stable occupiers and verified payments usually carries less risk than a higher headline return supported by weak records. The same principle applies to company transactions, where turnover, debt and asset support should all line up before the numbers are accepted.
- Check whether income is recurring or event-based.
- See how much depends on one tenant, customer, or contract.
- Test whether the income can be verified against documents and site reality.
Build a decision note that a lender can actually use
A useful portfolio review ends with a clear decision note. It should not be a bundle of comments that only the original analyst can interpret. The aim is to make the next step obvious: proceed, renegotiate, request more documents, or walk away. For lenders, this note should show the reason the asset fits, or does not fit, within the credit view.
Keep the structure simple. Start with the asset name, location, key strengths, key risks, and the action recommended. If there are several assets in one transaction, rank them. The strongest asset may still need conditions attached, while the weakest one may need to be excluded from the package entirely. This is where a clean review saves days of back and forth.
In practice, a good decision note answers one thing very clearly: would you be comfortable defending this file in front of a committee, a partner, or a credit committee?
- Summarise the top three strengths.
- List the top three risks in plain language.
- State the next action in one line.